Conversational AI for Real-Time Loan and Disbursement Status in India

Insights / Conversational AI for Real-Time Loan and Disbursement Status in India
Conversational AI Loan Disbursement Status India

Loan Status Is an Enterprise Support Question

For banks and NBFCs operating across branches, products, digital applications and servicing teams, “Where is my loan?” is rarely a single support interaction — borrowers ask about progress, verification, sanction, documentation and disbursement, and at enterprise scale every enquiry consumes service capacity.

The volume is material. RBI’s Annual Report 2024–25 says its Ombudsman offices received 2.96 lakh complaints during the year, with loans and advances the largest single category. The Ministry of Finance has also indicated that RBI’s own Complaint Management System is being upgraded with AI-enabled tools. For banks and NBFCs, this reinforces the value of making routine status information easier to access while keeping regulated grievance handling with the lender.

Why Manual Support Becomes Difficult at Scale

A manual status enquiry requires an agent to identify the borrower, locate the loan record, check its current stage and any pending condition, and explain next steps — repeated across thousands of enquiries, this creates avoidable service workload.

The same borrower may also move between WhatsApp, an app, the website, a contact centre or a branch. RBI’s digital lending framework treats servicing and customer service as part of the lending lifecycle and requires regulated entities to maintain grievance-redress mechanisms.

Conversational AI can handle the routine information layer while preserving a clear path to a human for cases requiring judgement, investigation or resolution.

How Conversational AI Retrieves Loan Status in Real Time

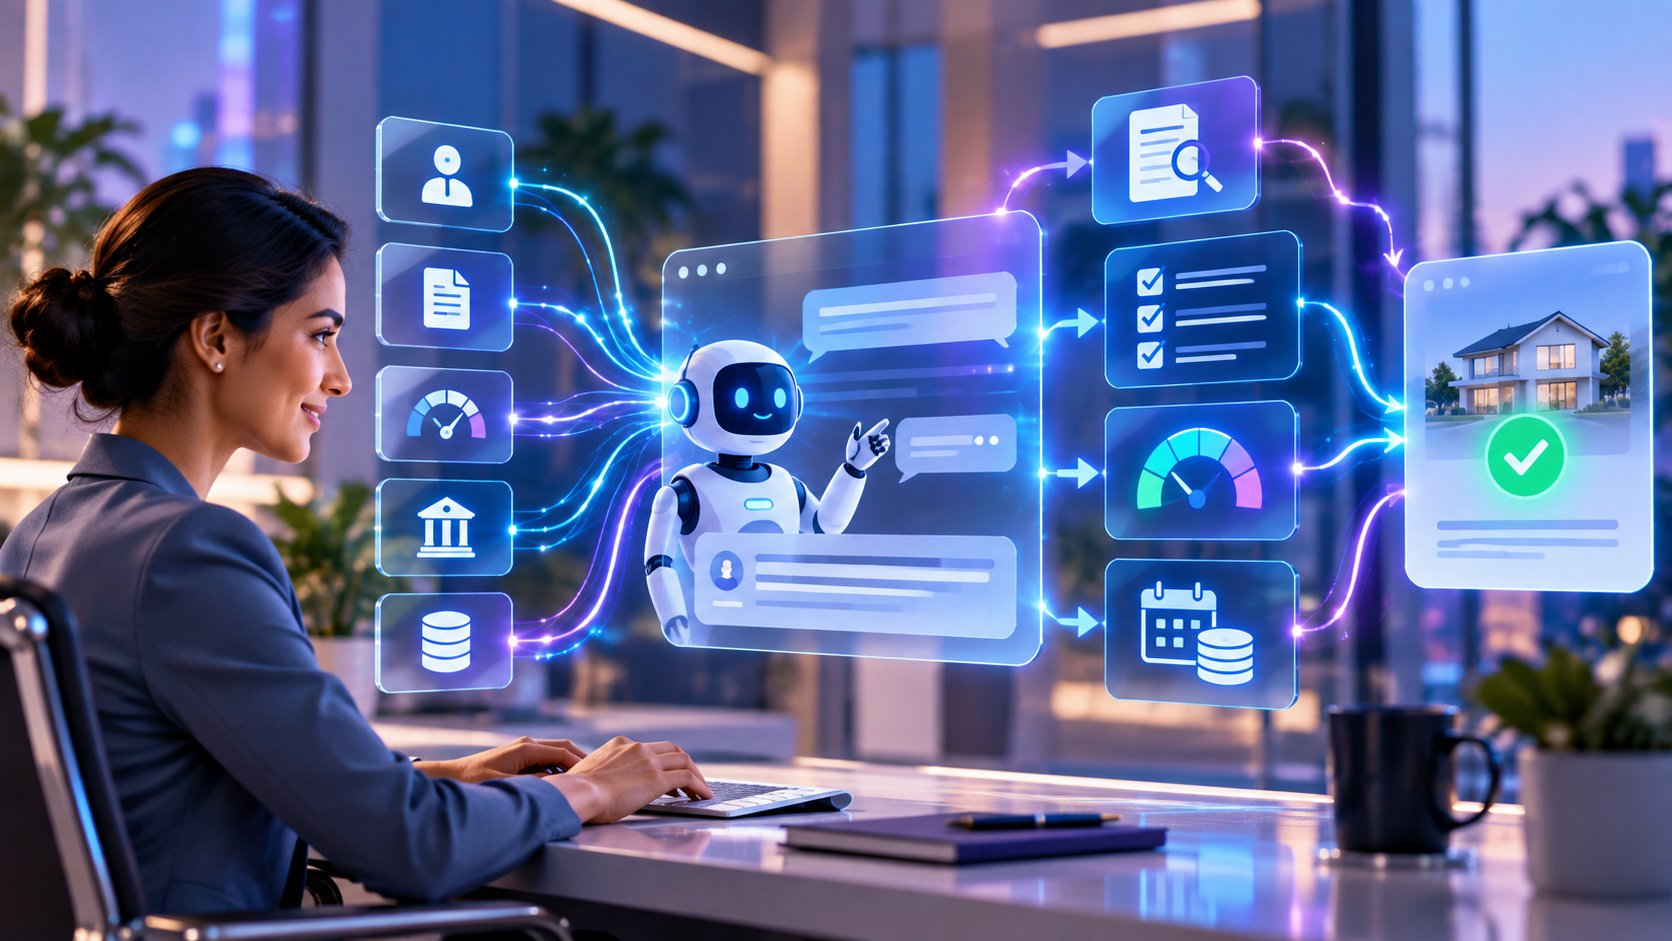
Conversational AI first identifies the customer’s request and verifies the information required to access the relevant loan record. It then retrieves the latest available status and presents it in customer-friendly language.

Instead of a generic “Your loan is under process” message, it can name the current stage, the latest recorded event and any action needed — reflecting the lender’s current records rather than a static FAQ.

Functionally, the process can be understood in five steps:

  1. Recognise the status enquiry.
  2. Confirm the borrower and relevant loan.
  3. Retrieve the latest status and associated information.
  4. Translate the status into a clear response.
  5. Identify whether the enquiry can be completed automatically or requires human attention.

Loan Journey Stage to AI Response

Loan journey stageWhat conversational AI can explain
Application receivedApplication reference, current processing stage and next expected step
Verification/documentationWhether verification is in progress and whether additional information is recorded as required
Credit assessmentCurrent assessment stage and any recorded next step that can be disclosed
SanctionedSanction status and the conditions or documentation recorded before disbursement
Disbursement pendingWhether disbursement is pending and the specific recorded reason, such as a pending condition or verification
DisbursedDisbursement status and the recorded disbursement date or relevant confirmation
Post-disbursement servicingRelevant servicing status, payment information or the next support step

The exact information available should follow the lender’s policies, access controls and regulatory obligations.

Explain the Reason for a Delay, Not Just the Status

“Processing” tells a borrower where the application sits. A useful response also explains what is happening.

A conversational response can distinguish between situations such as:

  • Additional documentation is awaiting submission.
  • Verification is still in progress.
  • A required check is pending.
  • A sanction condition remains outstanding.
  • Disbursement is awaiting completion of a recorded prerequisite.
  • The account has moved to a stage that requires specialist review.

This level of explanation helps service teams move from status reporting towards useful customer guidance. RBI’s fair-practice guidance has also emphasised timely disbursement and communication of relevant loan information.

Consistent Answers Across WhatsApp, App, Web and Voice

Enterprise lenders need the same underlying status to produce consistent answers across customer touchpoints. A borrower may begin on WhatsApp, continue through the mobile app and then call the contact centre. Conversational AI can support Instant Cross-Channel Attribution and Intent Mapping, so the customer receives the relevant status through the channel they choose.

This is where a Single Source of Living Truth can help keep the customer interaction current across touchpoints. The objective is simple: the borrower should receive a consistent explanation of the loan stage and next step, regardless of whether the enquiry arrives through messaging, web or voice.

Conversational AI Loan Disbursement Status India

When Conversational AI Should Hand Off to a Human

Automation should cover routine status enquiries; human teams handle cases needing judgement, investigation or customer-specific resolution.

A handoff is appropriate when:

  • The customer disputes the status or recorded information.
  • The borrower reports a discrepancy between channels or documents.
  • A case involves an exception requiring investigation.
  • The customer needs a decision or action outside the conversational AI’s authorised scope.
  • The enquiry involves a complaint or formal grievance.
  • The customer explicitly requests human assistance.

The handoff should carry the conversation and status context forward so the agent begins with case history rather than repeating basic questions — RBI guidance places grievance-redress responsibility with the regulated entity, including for digital lending.

Where Worktual’s AI Advanced Intelligence Platform Fits

Worktual’s AI Advanced Intelligence Platform can support enterprise loan-servicing journeys through Enterprise Data Sovereignty and Intelligence, bringing authorised customer and servicing information into a connected intelligence environment.

A Single Source of Living Truth can provide the current customer and loan context needed for conversational interactions, while access controls help ensure information is presented according to the lender’s governance requirements.

Across WhatsApp, app, web and voice, the platform can support Instant Cross-Channel Attribution and Intent Mapping for consistent status communication. Autonomous Orchestration can then support the movement from automated assistance to the appropriate human team when a case requires specialist attention.

For enterprise BFSI leaders, this combines accessible status information with governed human intervention — supporting customers consistently across products, branches and channels.

Conclusion

Loan and disbursement status is a high-frequency question with a clear place in enterprise conversational AI — retrieving current status, explaining specific next steps and routing exceptions to human teams gives banks and NBFCs a more informative servicing experience at scale.

The strongest model combines conversational assistance with human expertise, giving borrowers useful answers quickly while bringing specialist teams into the journey when the case calls for it.

Frequently Asked Questions

1. What can conversational AI tell a borrower about a loan?

It can provide the latest available loan stage, relevant status information, recorded next steps and, where appropriate, specific reasons for a pending stage or disbursement.

2. Can conversational AI provide loan disbursement status in real time?

It can retrieve and communicate the latest available status from the lender’s current records. The accuracy and timeliness of the response depend on the information available to the authorised system.

3. Which loan stages can conversational AI support?

It can support enquiries covering application receipt, verification, documentation, credit assessment, sanction, disbursement and post-disbursement servicing, subject to the lender’s policies and access controls.

4. When should a loan-status enquiry be transferred to a human?

A handoff is appropriate when the customer disputes information, an exception requires investigation, a decision or action falls outside the AI’s authorised scope, a formal complaint is raised, or the customer requests human assistance.

5. Can the same loan status be provided across WhatsApp, app, web and voice?

Yes. Conversational AI can support consistent status communication across multiple customer touchpoints when the relevant customer and loan context is available across those channels.

6. How can Worktual support enterprise loan-status servicing?

Worktual’s AI Advanced Intelligence Platform can connect authorised customer and servicing information, support a Single Source of Living Truth, provide consistent conversational assistance across channels, and support Autonomous Orchestration when a case requires human intervention.

Related Posts

AI Native Indian Healthcare

Why AI-Native Matters More in India’s Healthcare System Than Anywhere Else

Financial institutions operate in a highly competitive, regulation-driven, and margin-sensitive environment where revenue growth is no longer driven by acquisition alone. Banks, fintechs, and Non-Banking Financial Companies (NBFCs) continue to invest heavily in digital acquisition, yet face persistent challenges such as low onboarding completion, rising contact centre costs, increasing churn, and fragmented customer data. At the same time, customers expect instant responses, seamless onboarding, personalised financial guidance, and consistent service across digital and assisted channels. When these expectations are not met, conversion drops, churn increases, and cost-to-serve rises, often before the impact is fully visible in performance metrics.
Campaign Measurement Clicks vs Customer Value

Most Campaign Tools Still Measure Clicks. The Revenue Is Somewhere Else.

Financial institutions operate in a highly competitive, regulation-driven, and margin-sensitive environment where revenue growth is no longer driven by acquisition alone. Banks, fintechs, and Non-Banking Financial Companies (NBFCs) continue to invest heavily in digital acquisition, yet face persistent challenges such as low onboarding completion, rising contact centre costs, increasing churn, and fragmented customer data. At the same time, customers expect instant responses, seamless onboarding, personalised financial guidance, and consistent service across digital and assisted channels. When these expectations are not met, conversion drops, churn increases, and cost-to-serve rises, often before the impact is fully visible in performance metrics.
WhatsApp vs Email Indian Business

WhatsApp vs. Email for Indian Businesses: What the Real Numbers Show

Financial institutions operate in a highly competitive, regulation-driven, and margin-sensitive environment where revenue growth is no longer driven by acquisition alone. Banks, fintechs, and Non-Banking Financial Companies (NBFCs) continue to invest heavily in digital acquisition, yet face persistent challenges such as low onboarding completion, rising contact centre costs, increasing churn, and fragmented customer data. At the same time, customers expect instant responses, seamless onboarding, personalised financial guidance, and consistent service across digital and assisted channels. When these expectations are not met, conversion drops, churn increases, and cost-to-serve rises, often before the impact is fully visible in performance metrics.